Tribunal Grants Relief Following Departmental Notice
A taxpayer residing in Jaipur has successfully seen his financial penalty overturned after contesting a demand issued by tax authorities. The case involving the jaipur man income tax penalty cancelled highlight technical requirements during penalty proceedings.
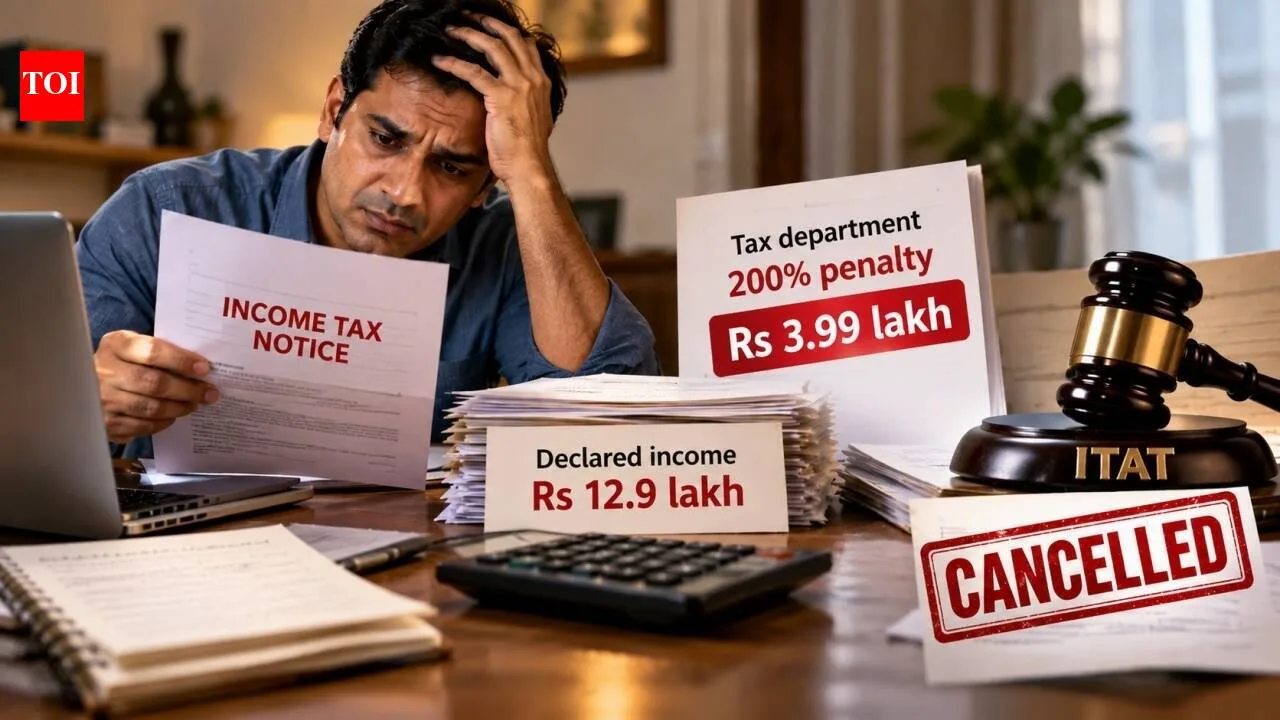
The situation began when the individual omitted to submit his routine income tax return. Following an official communication from the Income Tax Department, he submitted a return for the assessment year 2018-19, stating an income amounting to Rs 12.9 lakh.
Understanding the Penalty Dispute
The assessing officer concluded that the declared income would have stayed out of the tax framework if the department had not intervened. Consequently, proceedings were initiated under Section 270A of the Income Tax Act.
Because the tax payable on the reported amount was evaluated at approximately Rs 1.99 lakh, authorities levied a full 200% fine totalling Rs 3.99 lakh for alleged misreporting. Although the Commissioner of Appeals supported the decision, the taxpayer escalated the matter to the Income Tax Appellate Tribunal.
Why the Tribunal Quashed the Fine
On September 23, 2026, the ITAT Jaipur ruled in favor of the appellant. According to legal experts, the core issue centered on the omission of specific statutory details within the official paperwork.
- The assessment order lacked proper satisfaction regarding which specific part of Section 270A(9) was supposedly violated.
- The penalty notice failed to identify the exact clause under which the individual was being penalized.
- Tribunal members noted that failing to inform a taxpayer of the precise legal provision vitiates the entire penalty procedure.
Legal Precedents and Final Outcome
To substantiate its decision, the tribunal referenced prior judicial rulings, including a judgment from the Rajasthan High Court. Furthermore, the tribunal noted that the taxpayer's declared income had been accepted without any variations, and no revenue loss was sustained by the department.
Ultimately, the ITAT Jaipur concluded that the procedural lapses by the assessing officer invalidated the penalty, leading to the final order setting aside the financial penalty.
Sources: The Times of India, The Economic Times, Upstox.