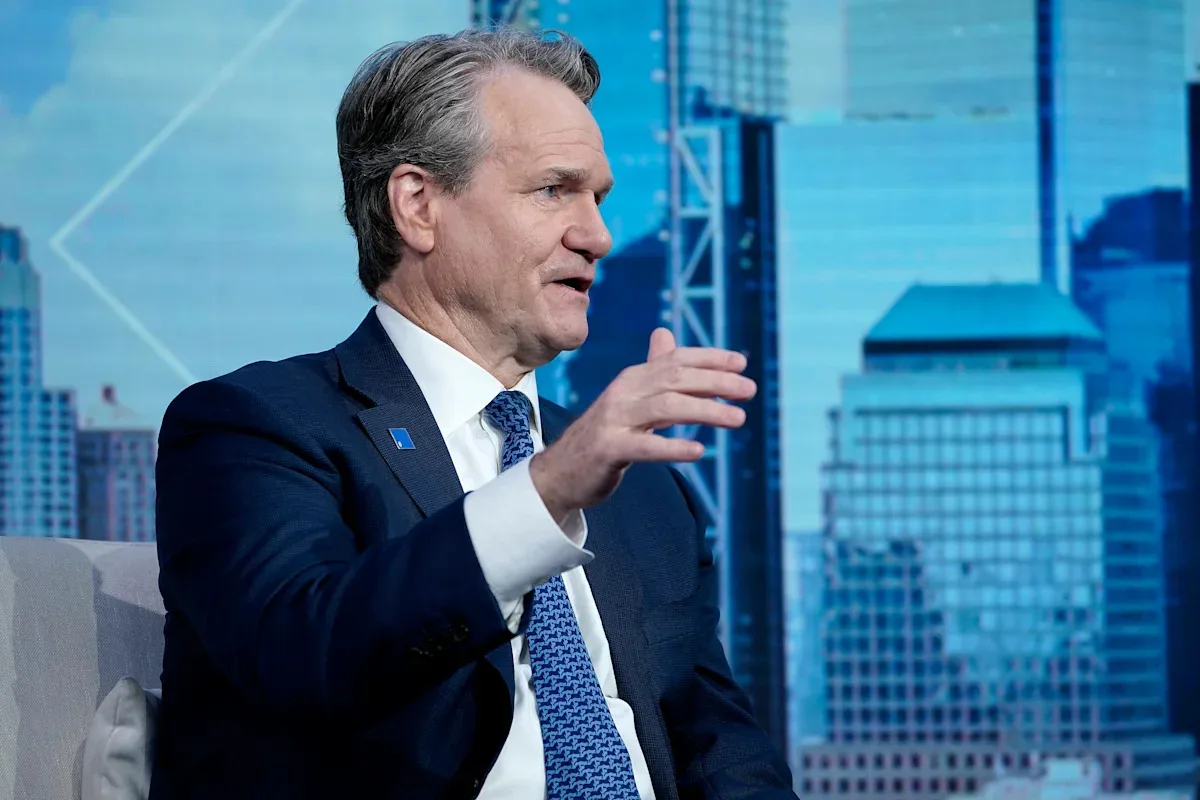
Federal regulators have penalized Bank of America over $1.2 billion for widespread deficiencies in monitoring illicit transactions and reporting suspicious funds. The enforcement actions highlight major structural breakdowns across the institution's compliance protocols.
As part of the bank of america fine money laundering investigation, authorities revealed that the nation's second-largest lender failed to adequately review trillions of dollars in transfers.
Treasury Department and Regulatory Penalties
The Financial Crimes Enforcement Network issued a $1.2 billion penalty, marking the third-largest fine in Treasury history. Additionally, the Office of the Comptroller of the Currency imposed a $750 million penalty, which will be credited directly against the FinCEN assessment rather than stacked on top of it. A separate sanctions settlement of $11.6 million brought total financial penalties past $1.21 billion.
Treasury Secretary Scott Bessent emphasized that even the largest financial institutions remain subject to federal law.
Details of the Suspicious Activity Failures
According to federal officials, the institution neglected to report upwards of $5 billion in suspicious financial movements. This included more than $1 billion tied to national security priorities, narcotics trafficking, fraud, and Chinese money-laundering networks. Regulators noted that leadership prioritized revenue generation over compliance resources, leaving questionable transfers unexamined for long stretches.
FinCEN noted that Bank of America acknowledged willfully violating the Bank Secrecy Act. Furthermore, investigators found that the lender effectively outsourced substantial detection duties to law enforcement and other banking institutions.
Market Impact and Financial Response
Following the disclosure, the bank of america stock dipped over 2% in after-hours trading. The lender announced plans to log a non-tax-deductible charge of $1.2 billion, affecting third-quarter net income by approximately 17 cents per share, ahead of its scheduled earnings report.
A spokesperson for the Charlotte, North Carolina-headquartered lender stated that financial crime compliance remains a critical responsibility. The representative added that the institution has deployed thousands of personnel and poured billions into technology upgrades to address the shortcomings.
Sources: Yahoo Finance, The Washington Post, Reuters.